

To most leaders, the concept of “pay for performance” seems logical. We think that financial rewards will naturally incentivize people to work harder. And the company should be a meritocracy, where the superstars are paid more than the slouches, right?
Unfortunately, pay-for-performance programs almost always cause harm in practice. I’m a little surprised that the majority of companies still use them.
When an employee hears an employer say “We pay for performance,” the employee thinks, Great! If I work twice as hard as the person at the next desk over, I should make twice as much.
But what the employer actually means is closer to: If you work twice as hard as the C-player at the next desk over, you’ll get a 5% raise at year-end, and they’ll get a 3% raise.
This unspoken misalignment creates all sorts of grief. Once you establish the idea in the employee’s head that their pay reflects the quality of their work in comparison to the work of their peers, you’ve created an expectation that can never be truly fulfilled:
In the best case, the employee receives only marginally more pay than a colleague they regard as a bozo, and they see this as unfair.
In the worst case, they don’t receive more pay at all—and then feel it is doubly unfair.
The root issue is that, for most jobs in the modern workplace, there is no objective measure of performance. It’s not like the NBA. Knowledge-work jobs are deeply entwined with each other and difficult to track; thus, it’s 100% up to the manager to decide who gets paid more. In the absence of something like a perfect “widgets produced per person” metric, this becomes an exercise in the manager’s subjective judgement. This is almost always perceived by employees as influenced by oversights, misunderstandings, and favoritism.
To my mind, this is the real casualty of pay-for-performance: the employee-manager relationship. Yes, incentive programs can also cause people to sandbag, focus on easy metrics, and even engage in unethical behavior. But once the core of trust in the employee-manager relationship is broken, you have a disengaged employee and a frustrated manager.
Pay-for-performance erodes that trust rapidly. Even employees who benefit usually feel they are not being paid commensurate to their outperformance of the team’s worst player.
So what’s the solution? Here are some general principles to follow:
Decouple pay and performance entirely. Do not state or imply that the organization pays great performers more. Do not link employee appraisals or goal achievement with pay raises or bonuses. Instead, communicate that high performance is expected of every employee. When managers do have conversations about pay with employees, it should happen in a separate meeting.
Compensate employees based on market rates. Working with your HR head, understand what the market pays for the various types of talent you need, and pay in line with the market. This is a far more consistent and unbiased way to determine salaries. You may decide to pay overmarket or undermarket across the board as part of a broader talent strategy, but these decisions should be pegged to market value and applied consistently.
Don’t keep the bozos. Now, in a company where everyone’s total compensation is in line with the market, you may still encounter situations where an A-player is frustrated by the presence of C-players on the team. But instead of keeping the C-players around and just paying them a little less, the better approach is to quickly coach them into B-players—or move them off the team. You will never have all A-players on a team, and solid B-players are important. But if you’re paying market rates across the board, you can’t afford to coddle the low performers.
This system works because it takes the pressure of subjective compensation discussions off managers and their employees and instead allows them to focus on achieving outcomes together. It also creates an actual sense of fairness. It encourages managers to identify those employees who aren’t really earning their market value and let them go when they don’t respond to coaching.
A-players are still the manager’s priority. They should be rewarded in other ways—with greater responsibility, with more development opportunities, with proper praise and recognition. But claiming to pay them more for their achievements is a strategy that almost always backfires.
The Rundown
JP Morgan just increased its estimate of the likelihood of a recession by year-end to 35%. That's up from 25% last month. In keeping with that, we see recessionary indicators running throughout this week's roundup.
Uh-Oh! You’re Late.
U.S. consumers continue to become more financially constrained.
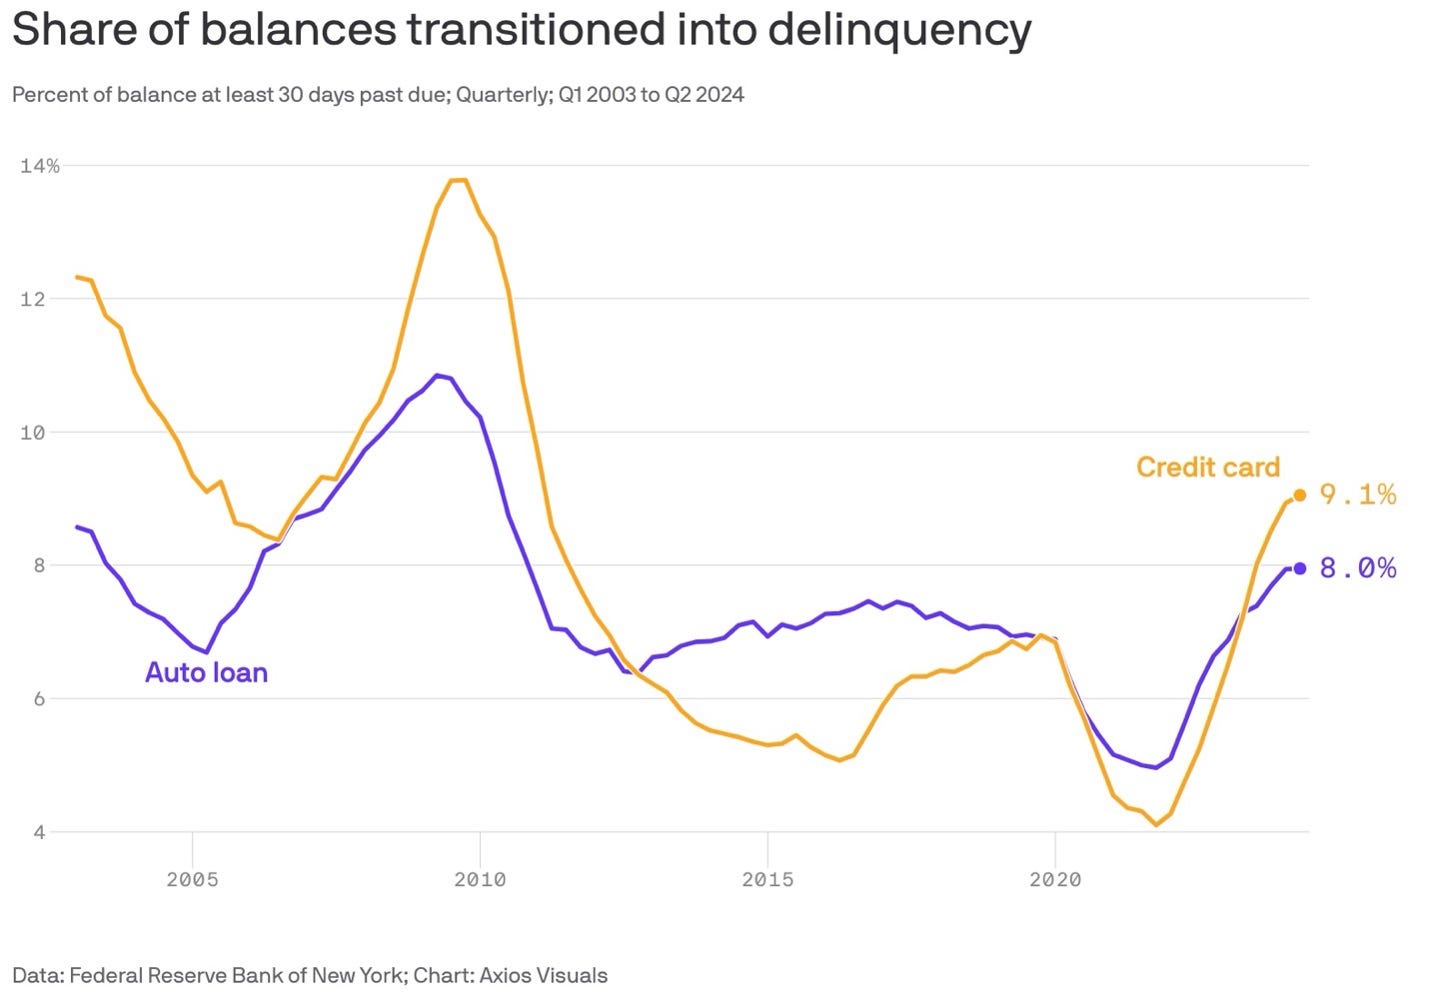
A new report from the New York Fed sheds light onto the troubling situation for millions of Americans. Consumer credit rose by $8.9 billion (expectation was $9.7 billion) and the use of credit in the 12 months ending in June 2024 grew by 1.9%. Interestingly, the use of credit year-over-year dropped by ~5.3%. Some economists argue that the use of credit only rises this slowly (sub-2%) over this amount of time when the economy approaches a recession.
Digging into the numbers, 8% of auto loan balances and 9.1% of credit card balances became newly delinquent (less than 90 days late but over 30 days) last quarter. Delinquency rates for credit cards have also increased ~2% year-over-year. Credit card balances shifting to “serious” delinquency status (over 90 days late) was measured at 7.2% for Q2 2024.
These look to me like signs we could be heading into a recession in Q4.
Employment Costs and Job Openings Shrink
Demand for labor has waned in a slowing economy.
The Employment Cost Index (ECI) is regarded as the most accurate measure of U.S. labor costs, and it grew at less than 1% in Q2 2024. This is the second time in the last three quarters that labor costs have been reported below 1%. This could indicate reduced demand for labor in a slower-growing economy. Wage growth continues to slow down as private-sector wages grew at a 3.4% annualized rate, which is the slowest since September 2020. Many economists believe the Fed would like to see these costs slow even more as wages and benefits rose an average 2.7% per year in the three years preceding the pandemic.
A recent ADP report showed that 122,000 jobs were added in July, the smallest gain in six months and at the same time the 12-month increase in pay for employees remaining at their existing job hit a three year low of 4.8% in July. Half of all the jobs created were in trade and transportation, while service workers across several industries (restaurants, hotels, etc.) supplied the remaining jobs. Employment fell in many sectors, mainly media, white-collar business, and manufacturing. Overall, the number of industries actively hiring has shrunk, and job openings in the U.S. have fallen by 1/3 in the past two years.
ISM Shows Services Expansion
A slight service sector boost doesn't necessarily allay recession fears.
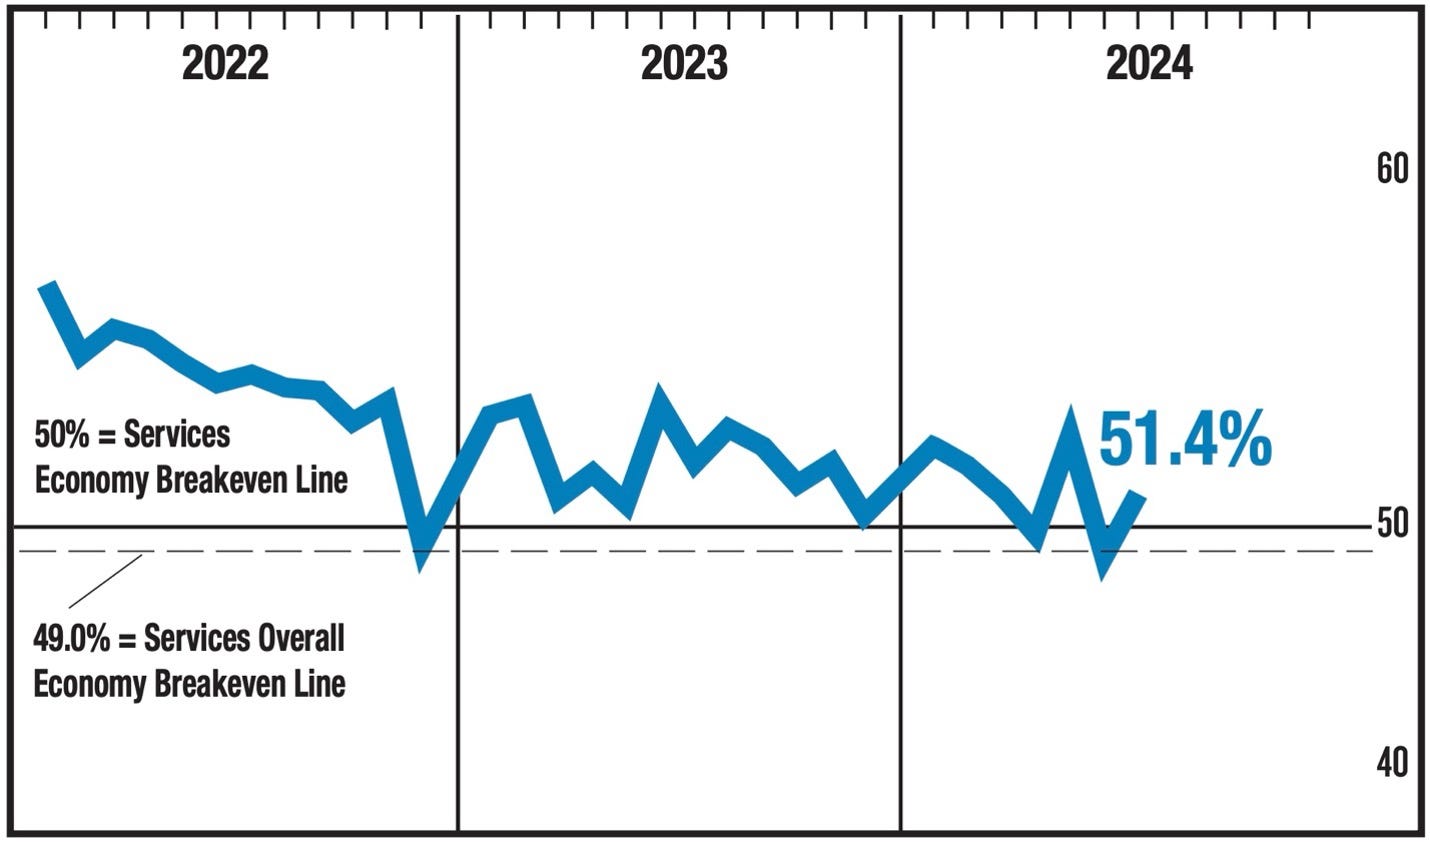
The service economy in the United States is expanding according to the latest ISM survey, which is in line with the ADP report indicating that most jobs are coming from service-based businesses. The ISM number came in at 51.4% for July after a reading of 48.8% for June. (A reading greater than or equal to 50% qualifies as expansion.) The majority of businesses shifted their responses to “flat or expanding gradually” from “flat or contracting gradually,” and the index put up some impressive numbers. The new-orders index rose 5.1 points to 52.4%, production rose 4.9 points to 54.5%, and employment increased 5 points to 51.1% which broke a five-month streak of negative readings, and currently sits at the highest level since fall 2023. Does this run counter to the other recessionary trends we’re seeing? A little—but if you look at the below chart, you see the trend still moving steadily down.

"The way people solve problems is first by having an enormous amount of commonsense knowledge, like maybe 50 million little anecdotes or entries, and then having some unknown system for finding among those 50 million old stories the 5 or 10 that seem most relevant to the situation. This is reasoning by analogy." —Marvin Minsky
“Finding out that you are wrong is even more valuable than being right, because you are learning.” ―Amy Edmondson
“It is not the content of a company’s values that correlates with performance, but the strength of conviction with which it holds those values, whatever they might be.” —Jim Collins